The youngtimer tax rule changes in 2027: what it means for your company car
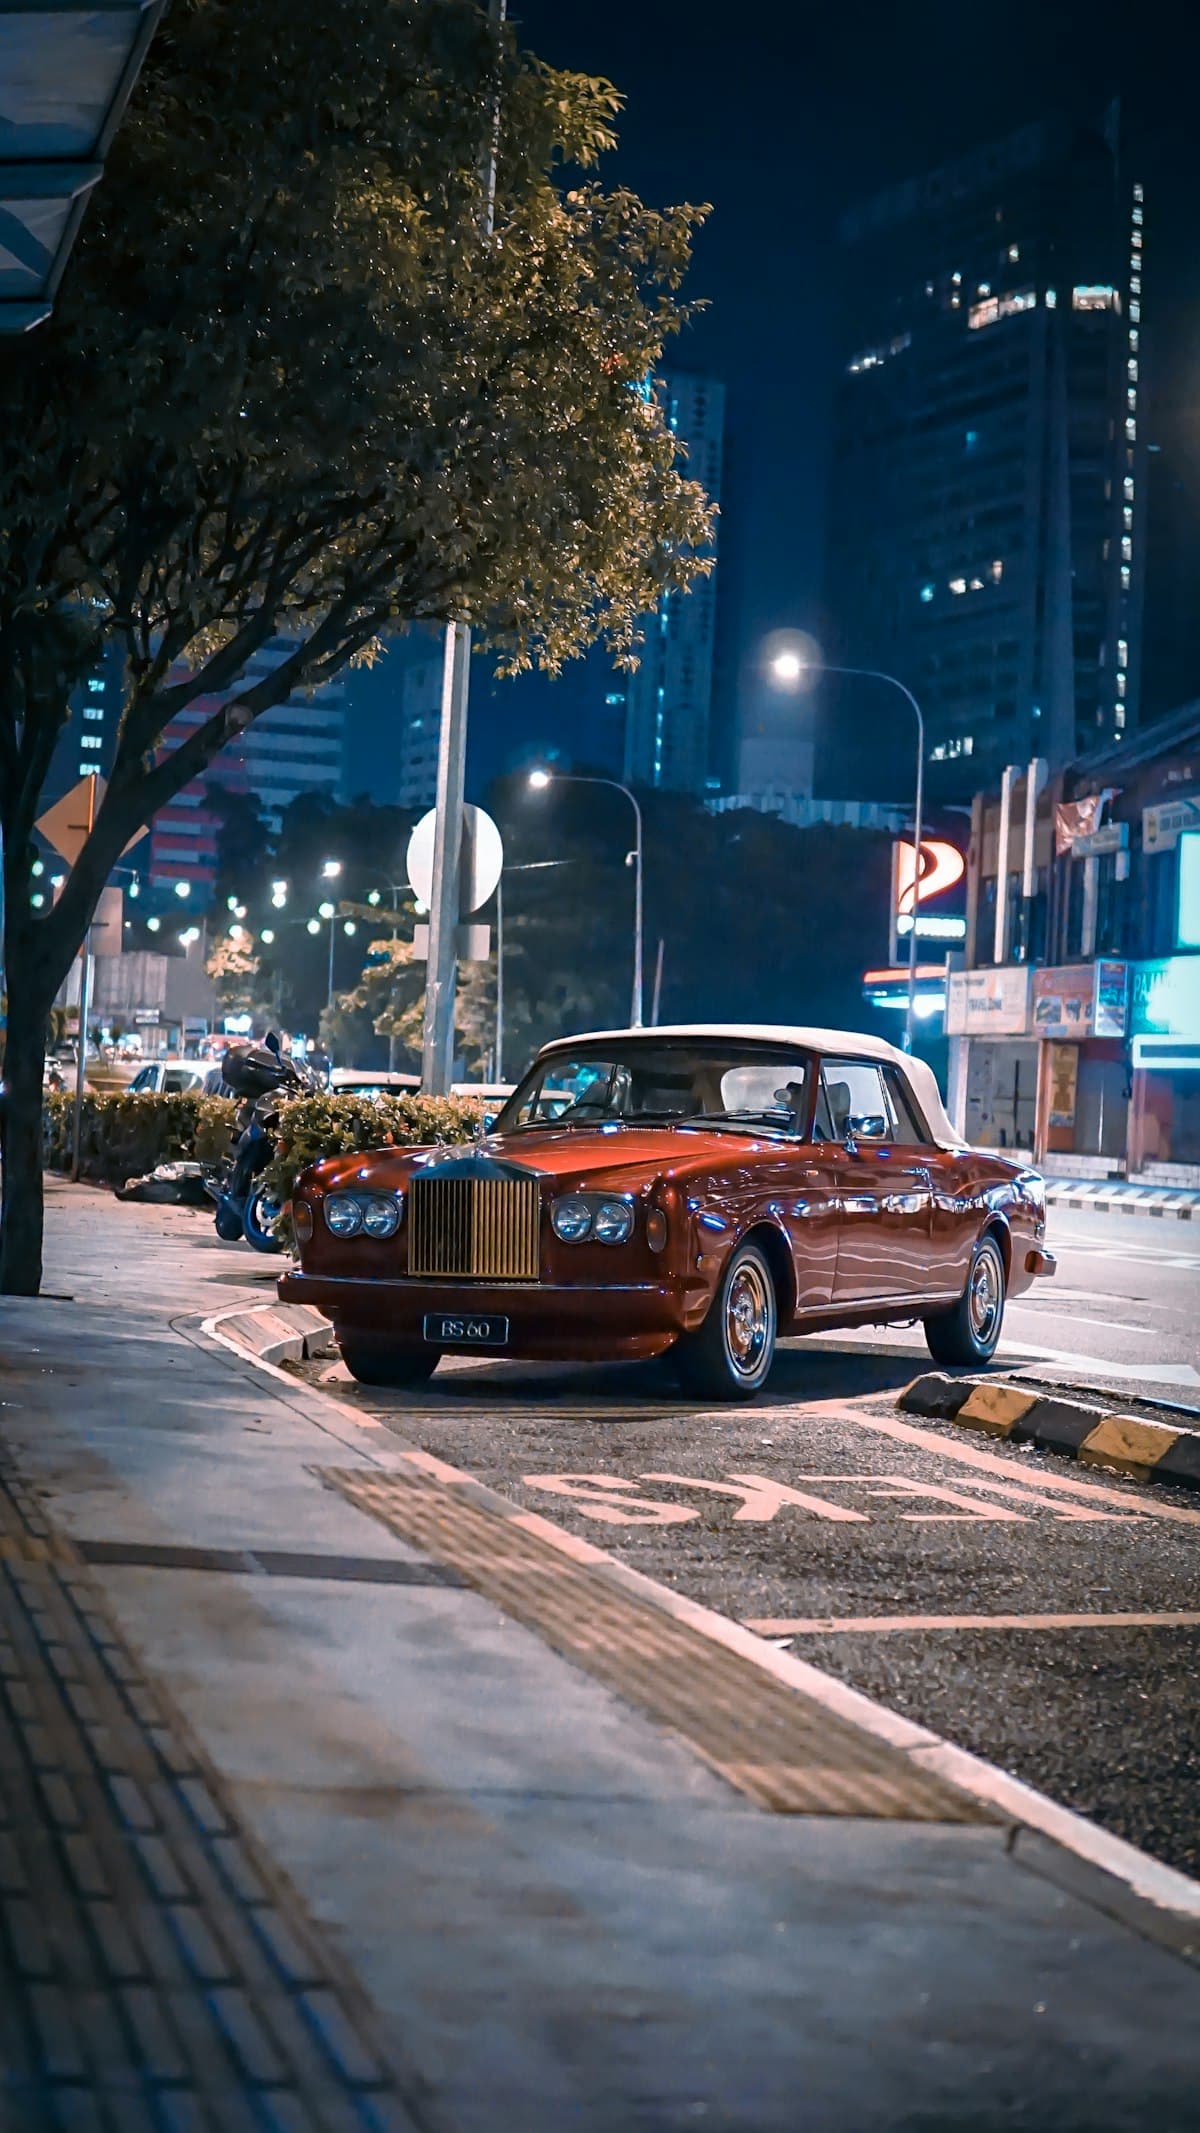
If you drive a company car that qualifies as a youngtimer, you benefit from a relatively low bijtelling. That rule was already tightened by the 2026 Tax Plan and is cut back sharply again from 2027. Here is what applies now, what the statute says for 2027, and why it is worth following the political decision-making a little longer.
Update 19 September 2026: government opts for 17 years in 2027 and 20 years in 2028
On Budget Day (15 September 2026) the government made its choice. Under the 2027 Tax Plan bill the age threshold does not go to 25 years, but to 17 years on 1 January 2027 and to 20 years on 1 January 2028. For cars that were already in use by the same person before 2026 and turn 17 in 2027, the youngtimer rule may be applied for the whole of 2027. This is a proposal: both houses of parliament still have to vote on it. Until they do, the 25-year threshold formally remains on the statute book. The 2027 amounts in this article and in the calculator are still based on that statute; the calculator will only be changed once the proposal has been adopted.
How the rule works today
For a youngtimer you calculate the bijtelling on the car's current market value rather than its original catalogue value, at a rate of 35%. Because the market value of an older car is usually a fraction of its list price, the resulting amount is considerably lower than for a regular company car. Watch the age threshold: up to and including 2025 the rule applied to cars first put into use more than 15 years ago, but since 1 January 2026 that threshold is 16 years.
What the statute says for 1 January 2027
The 2026 Tax Plan raises the age threshold from 16 to 25 years with effect from 1 January 2027. Cars between 16 and 25 years old will then no longer fall under the 35% rule but under the standard 22% of the original catalogue value. Only cars first put into use more than 25 years ago keep youngtimer status. The date of first use is what counts, not the model year or the date you bought the car.
What that means in euros
Take a car with an original catalogue value of EUR 45,000 and a current market value of EUR 8,000. As a youngtimer the bijtelling is 35% of EUR 8,000, or EUR 2,800 a year, just over EUR 233 a month. If the same car falls outside the rule in 2027, it becomes 22% of EUR 45,000: EUR 9,900 a year, or EUR 825 a month. Crucially, those are not amounts you pay but amounts added to your profit. What you actually part with is that figure times your marginal tax rate - at the 48.29% marginal rate that applies to many freelancers in the second bracket, the tax burden in this example rises from roughly EUR 113 to roughly EUR 398 a month.
The bijtelling never exceeds your actual car costs
As an income-tax entrepreneur an important cap applies: the withdrawal never exceeds the car costs you actually incurred that year, including depreciation. If an old car costs you EUR 4,000 a year, the 2027 bijtelling is EUR 4,000 too, not EUR 9,900. That cap does not exist for director-shareholders and employees with a car owned by a BV. The VAT private-use correction, incidentally, simply continues; it has a limit of its own - the VAT you actually deducted - rather than the cap at the level of the car costs.
The last word has not been spoken
The increase to 25 years is on the statute book, but in March 2026 parliament adopted a motion asking the government for a gentler transition. In June 2026 the government sketched four variants, ranging from grandfathering cars first used before 31 December 2010 to a stepped path via 17 years in 2027 and 20 years in 2028. It is separately working on a greentimer or eTimer scheme for used electric cars, to stop them leaving the country en masse after four or five years. A final decision is expected in the 2027 Tax Plan, presented on Budget Day.
Thinking of moving the car to private assets?
In early 2026 the Belastingdienst knowledge group confirmed that this change of law can be grounds for reclassifying the car on 1 January 2027, provided you make it plausible that you would have chosen differently under the new rules. That is a real option, but it comes at a price: on transfer to private assets you settle tax on the difference between the book value and the market value. Work that out in advance.
Want to know what this means for your car, including the VAT correction and the comparison with keeping the car privately? Our in-depth article on company car bijtelling includes a calculator that puts 2026 and 2027 side by side. Prefer to go through it together? Get in touch.
This article is intended as general information and doesn't replace personal advice. Tax rules and figures change regularly — get in touch for advice tailored to your situation.